
Share
Christmas bonuses could cost minimum-wage workers in Romania their tax break
13.11.2026
4 min
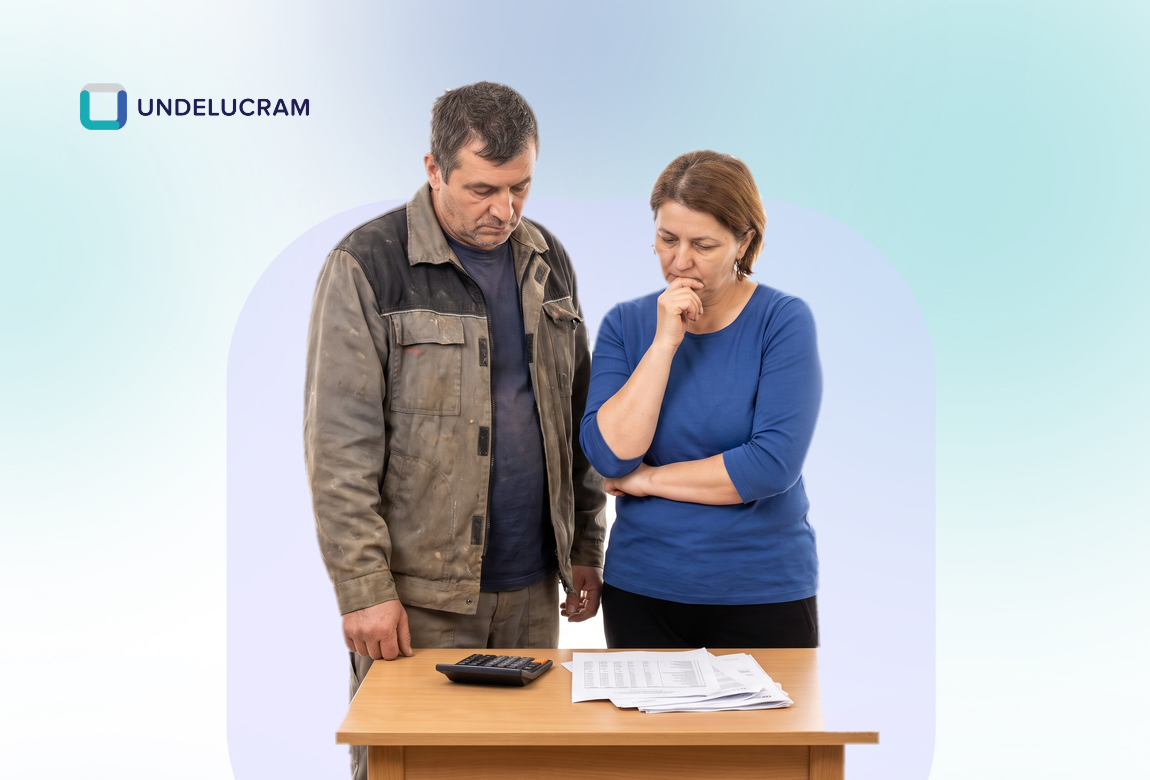
Between Romania's gross minimum wage of 4,325 lei (RON), in force since 1 July 2026, and the 4,600-lei ceiling set for the tax relief, there are exactly 275 lei of headroom. That is all the room an employer has each month until 31 December 2026 for allowances, overtime or bonuses paid to a minimum-wage employee before that employee loses the tax exemption on 200 lei of income.
The calculation becomes urgent now, as companies set their year-end bonuses. A Christmas bonus paid without a prior simulation can leave some of the lowest-paid staff with less take-home pay than everyone expected. And that is a reward-policy decision, not just a payroll software setting.
What the relief covers and who qualifies
The measure is set out in Article III of Government Emergency Ordinance (OUG) no. 89/2025. For income relating to the period from 1 July to 31 December 2026, 200 lei per month can be exempt from income tax and mandatory social contributions (CAS, the pension contribution, and CASS, the health insurance contribution). For the first half of the year, when the minimum wage was 4,050 lei, the exempt amount and the related gross income ceiling are not governed by OUG 89/2025 and are outside the scope of this article.
The conditions are checked monthly and must all be met at the same time:
-
Full-time, in the employee's main job. Part-time contracts and income from a secondary job are not covered by the relief.
-
Contractual base salary equal to the national gross minimum wage applicable in that month. This level is checked excluding allowances and supplements.
-
Gross income earned under the same contract of no more than 4,600 lei in that month. This includes everything actually paid, bonuses included.
-
Pro-rata calculation for employees who join or leave during the month: the exempt amount applies only to the eligible period.
The ordinance excludes meal vouchers, holiday vouchers and the statutory food allowance from the ceiling test. That detail matters for any discussion about how year-end rewards are structured.
The threshold is a cliff, not a slope
The relief does not taper off as income rises. An employee whose gross income reaches 4,600 lei stays within the ceiling. One who reaches 4,650 lei after a bonus loses the relief for the entire month, and taxes are calculated on the full amount.
To estimate the impact correctly, you need to understand what the exemption is worth. The 200 lei do not appear as extra money on the payslip: they are the portion of gross income on which no taxes are due. The gain in net salary is the difference between the taxes owed with and without the relief. The actual gain depends on the applicable social contribution rates and income tax, calculated on the 200 exempt lei.
The practical consequence: a bonus of a few hundred lei gross that pushes the month's income above 4,600 lei loses a good part of its net effect, because that month the employee also pays the taxes they would otherwise have been spared. The difference shows up immediately in the employee's take-home pay.
Where the risk sits in the organisation
Holiday bonuses are only the most visible case. The 275-lei margin is also eaten up by recurring items: night-shift allowances, paid overtime, weekend premiums or hazardous-conditions allowances. In companies running shift work, a minimum-wage employee may already be close to the ceiling before any bonus.
Then there is the perception problem. Employees see the net figure, not the formula. If a bonus announced as a gesture of recognition yields less take-home pay than expected, the message that sticks is not about tax but about the employer's fairness. In minimum-wage roles, where staff turnover is high anyway and a few dozen lei can trigger a move to a competitor, such a surprise quickly spreads among colleagues and, quite often, onto employer review platforms.
What HR and payroll can do before 31 December
Companies that handle this well treat bonuses for minimum-wage staff as a separate decision, calculated individually. A few options to assess:
-
Simulate the month, not just the bonus. Before approval, add up all the estimated gross income under the contract for that month: base salary, allowances, overtime and the proposed bonus. Only then can you see whether the employee stays below 4,600 lei.
-
Calibrate the amount. Either the bonus fits within the available margin, or it is large enough to clearly offset the lost relief. The middle ground, a small bonus that barely crosses the ceiling, is the least efficient option for both sides.
-
Tools excluded from the ceiling. Meal vouchers, holiday vouchers and the food allowance do not count towards the ceiling test, so they can be considered as alternatives, within legal limits and internal policy.
-
Which month the income belongs to. The relief applies to income relating to July through December 2026. Before moving a payment from one month to another, check with your tax adviser which month the bonus is attributed to and what regime will apply after 31 December 2026, which depends on future legislative decisions.
-
Communicate explicitly. A short note explaining to employees why their net pay looks the way it does prevents more HR queries than any later correction.
Make the call on the numbers, not on reflex
The 200-lei relief is a temporary measure, with small stakes on paper and large ones in the eyes of the lowest-paid employees. For HR, the lesson goes beyond December: any fixed tax threshold turns a well-intentioned reward into a risk unless it is calculated contract by contract.
To see how pay levels at your company compare with the market, especially for roles close to the minimum wage, the employee-reported data in Salariometru offers a benchmark built from real salaries, not estimates.
Share
What I read is worth it:
Read all the articles about
Balance Career planning Economic HR Metrics Labour market Legislative Negotiation Workforce planningArticle written by:
 Undelucram.ro
Comments
0 comments
No comments! Be the first to comment on this article!
Access your account and add your comment
Balance
Subscribe to the Newsletter
Read articles of interest from Undelucram.ro contributors
