Share
CAS dispute for part-time workers before D112: do sick-leave days count toward the minimum threshold?
18.08.2026
4 min
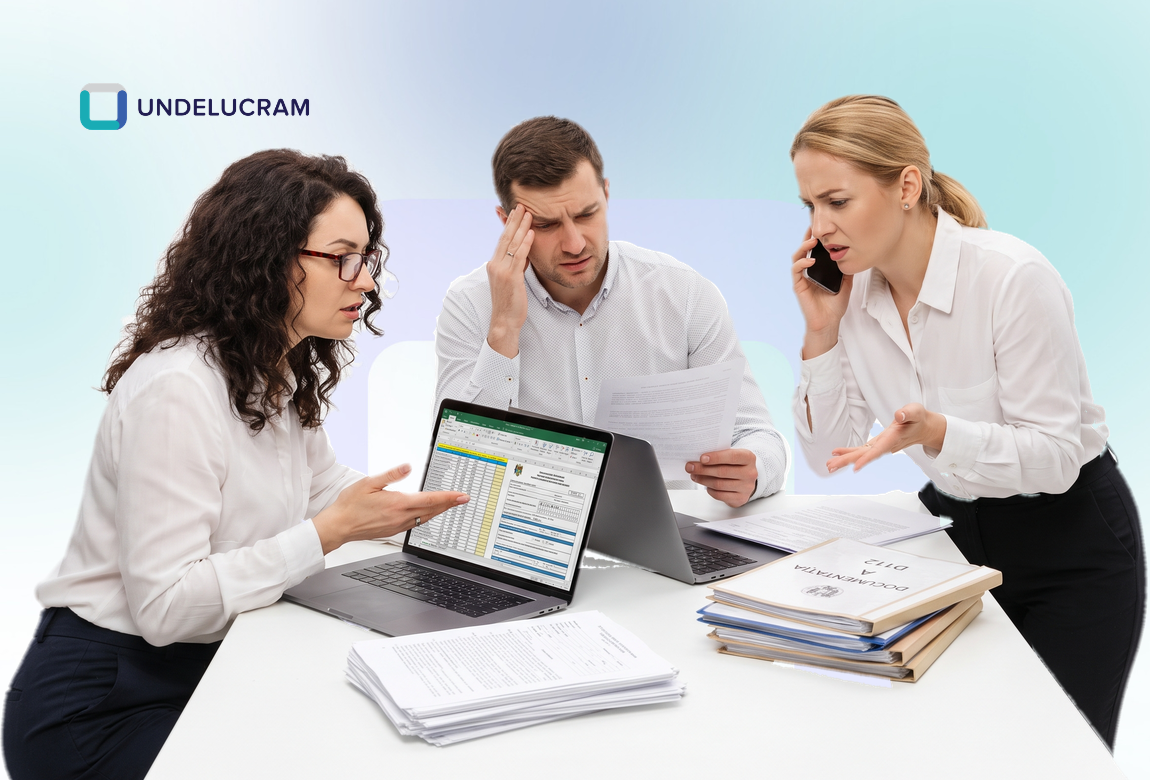
Just days before the submission deadline for Declaration 112 (D112), Romania's monthly payroll tax return, employers with part-time staff on sick leave are facing a technically complex problem with real financial consequences. ANAF's (the Romanian National Agency for Tax Administration) own technical documentation for the declaration appears to contradict Article 146 of the Fiscal Code on how the minimum CAS (pension contribution) threshold should be calculated. The Chamber of Fiscal Consultants (Camera Consultanților Fiscali, CCF) has raised the alarm publicly and is calling for urgent clarification before the validation system begins rejecting filings or generating unexpected contribution differences.
The core issue is straightforward to describe but difficult to resolve independently: if sick-leave days are counted as "days worked" when calculating the minimum CAS threshold, employers end up paying a contribution top-up that the law, in the view of fiscal consultants, does not actually require. If sick-leave days are excluded, the declaration may be rejected by ANAF's validation system altogether.
What the Chamber of Fiscal Consultants is challenging
The flashpoint is Article 146, paragraph (5^6) of the Fiscal Code (Codul fiscal), which sets the minimum calculation base for CAS on certain part-time employment contracts. ANAF's technical documentation for Declaration 112, circulating under the reference "structura_D112_0726_030826", uses a formula that includes both days actually worked and days of sick leave (concediu medical, CM) to establish that threshold. The CCF argues that this rule has no basis in the statutory text.
The consultants' wording is unambiguous: "The rule introduced in the technical documentation does not follow from the text of Article 146, paragraph (5^6) of the Fiscal Code, it actually appears to contradict it." Their legal argument rests on a foundational principle of Romanian labour law: during sick leave, the individual employment contract (contractul individual de muncă) is suspended. For that reason, the consultants say, those days should not be factored into a threshold that is designed to reflect actual working activity.
The practical effect of ANAF's formula, if it remains embedded in the validation system, is that the minimum threshold rises, and the gap between the CAS actually due on the part-time income and the CAS owed at the higher threshold falls on the employer. In plain terms: the company pays a higher contribution for a day on which the employee was not working, but was on sick leave.
For HR and payroll teams: what to decide right now
Until the Ministry of Public Finance or ANAF issues an official clarification, you are caught between two asymmetric risks. If you file Declaration 112 following the CCF's interpretation, excluding sick-leave days from the threshold formula, there is a risk that the validation system rejects the return or flags differences you will have to explain later. If you file in line with ANAF's technical documentation, you pay more than the law, according to the consultants, requires, and recovering the difference later means an administrative procedure.
Practical steps you can take in the short window before the deadline:
– Quantify your exact exposure: identify how many part-time employees were on sick leave during the reporting month and estimate the CAS difference between the two interpretations. Without that figure, you cannot make an informed decision.
– Document your reasoning internally: whichever approach you choose, keep a written record, an internal memo or a confirmed email exchange with your fiscal consultant, explaining which interpretation you applied and on what legal basis. If a correction is required later, you have a decision trail.
– Check the workflow with your fiscal consultant or accounting firm: this is especially important if you outsource payroll. Ask directly which formula they are applying for part-time cases involving sick leave and which version of the technical documentation they are working from.
– Monitor official communications: the CCF has publicly asked the Ministry of Public Finance and ANAF to publish clarification before the filing deadline, precisely to avoid interest charges, penalties, or validation errors. If a notice is issued before you submit, apply it retroactively to returns already prepared.
The deeper implication, beyond this specific case, is one of tax governance and predictability. When technical documentation introduces a rule that the statutory text, on the consultants' reading, does not support, employers end up bearing the cost of legal uncertainty. For businesses with large numbers of part-time workers, retail, hospitality (HoReCa), services, BPO, the cumulative difference is not trivial and hits the payroll budget directly.
For part-time employees: why this affects you too
If you are on a part-time contract and had sick-leave days in the reporting month, this dispute does not directly change the net pay you receive in hand, but it can affect how your social insurance contribution (CAS) is reported on your behalf. CAS is the contribution that counts toward your state pension, so any discrepancy in how it is declared has long-term implications.
Useful steps you can take:
– Check your payslip: make sure that your sick-leave days appear correctly as a period of contract suspension, not as days worked. The difference will be visible in the contributions section and in the gross salary calculation.
– Ask your HR or payroll department calmly which formula they are using for CAS in that month, especially if you had several days or more of sick leave. This is a technical clarification, not a confrontation.
– Keep your documents: medical certificates, payslips for the month in question, and any employer statements. If a correction is issued later, these records will help you reconstruct the full picture.
If you want to understand how gross salary translates into net pay and which contributions are withheld at source, you can use the gross-to-net salary calculator.
What to watch in the coming weeks
Three developments are worth tracking. First: whether the Ministry of Public Finance or ANAF issue an official communication confirming or rejecting the interpretation embedded in the technical documentation. Second: whether the technical documentation is quietly revised without public notice, in which case employers who already filed under the old formula may need to submit corrections. Third: whether the matter escalates into a formal procedure, an official response to the CCF's complaint, a clarifying statutory instrument, or, in time, a court ruling.
The case is narrow as a technical question but significant as a matter of principle. In a well-functioning tax administration, the technical documentation for a tax return should not introduce rules that the statute itself does not provide for. When it does, the cost falls predictably on employers, and, indirectly, on employees. Until the clarification arrives, the best decision is the documented one: know what you applied, know why, and keep the legal basis within reach.
Share
What I read is worth it:


Read all the articles about
About the crafts Editorial Employee experience Career planning Balance HR Metrics Labour market Statistics LegislativeArticle written by:
 Undelucram.ro
Comments
0 comments
No comments! Be the first to comment on this article!
Access your account and add your comment
About the crafts
Subscribe to the Newsletter
Read articles of interest from Undelucram.ro contributors
